 LIVE DEMO
USDC Paywall
Lock content behind a fraction-of-a-cent USDC payment, on your own Arc contract. Deploy it, become the onchain creator.
Ready now
$100Arc
 Try it live
Your own lending market without cliff liquidations: risky loans unwind in small steps, with a plain warning before each one.
Try it live, freeYour USDC is locked in a smart contract, not sent to us. The contract lets us collect it only if we deliver within 14 days of your payment (by 15 Nov 2026 if you pay today). After that date, if we have not collected it, you take it back yourself from My apps, no permission needed. Before it, only we can refund: if we miss the promised date, ask in My apps and we refund you from the contract. View the contract on BaseScan. This covers every payment, a reservation too: the funds are released to us only when we deliver.
Promised delivery: 6 Nov 2026 (counted from payment). Self-refund opens: 15 Nov 2026 (the contract deadline).
Add-ons are not part of this payment. Once your app is delivered you can request them from My apps, and you only pay if you say yes to the quote.
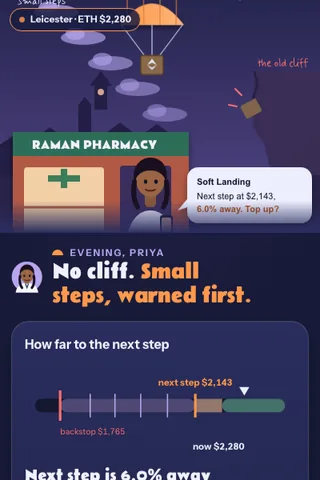
Priya Raman runs a pharmacy on Narborough Road in Leicester and borrowed USDC against her ETH to pay for a shop refit. In 2022 one liquidation took a fifth of her stack in a single block. On Soft Landing her loan unwinds in small steps if ETH falls, a Telegram message arrives before each step with how far away it is, and she can top up or repay before it happens.
The user app: borrow builder with a live step ladder, the next step meter, warnings by Telegram before each step, three playable market paths, top up and repay, history with receipts and a three tier paywall with simulated USDC checkout. Runs as an isolated market on Base and Arbitrum.
Reshape it entirely: new features, your flows, your brand end to end, integrations you need. We scope it with you.
Soft liquidation is not new: Curve's LLAMMA converts collateral gradually across price bands, and Fluid also unwinds risky positions in smaller pieces. What this adds is an owner run isolated market where each step is a fixed, small sale with a plain warning before it, a meter that shows how far the next step is in price and dollars, and a one tap way to stop it. Honest label: low novelty, the value is the warning loop and the ownable market.
Curve crvUSD and Llama Lend (LLAMMA soft liquidation), Fluid (smaller liquidations), DeFi Saver automation (automatic repay and boost on Aave), Aave and Morpho alerts from third party bots.
Checked with web searches in October 2026. A search is not proof that nothing similar exists, and the market moves fast, so we recheck before every build.
3 live races fit this app. Each one says why, with its prize and countdown. The rule on existing code is on the race page.
A lending market you own where falling prices unwind loans in small, warned steps instead of one cliff liquidation: borrowers see the next step coming, and you set the rules and earn from plans and interest.
Every buyer gets the same finished app. Basic branding and copy changes come through a quick form.
Your admin side: revenue, paywall editor, users, rules and the agent log.
Referral and growth mechanics, switched on when you are ready to grow.
Borrowers start free with one loan and Telegram warnings; Cushion and Treasury plans add channels, loans and team features. The market's reserve share of borrow interest goes to your treasury.
Reserve share of 5 to 15 percent of borrow interest (default 10 percent) to your treasury, shown on the borrow screen. Keepers earn a fixed step fee from each step; the owner does not take a cut of steps.
Prices are yours to set. Illustrative, not a promise of income.
Unlocked when your app is paid in full
Unlocked when your app is paid in full
Your brand, market name, collateral list, interest curve, step defaults, warning channels and integrations such as team signers, accounting export or a partner's white label market are scoped and priced together.
The recipe (how it is built, the data, costs, risks, build order, the pitch and the demo script) is unlocked when your app is paid in full.
People who borrow against crypto fear one thing most: a liquidation that sells a big slice of their collateral at once, with a penalty, often at night. Most lending markets still work that way, and alerts from outside bots arrive late or not at all.
This exists in parts. Curve's LLAMMA already converts collateral gradually across price bands instead of one hard liquidation, Fluid unwinds positions in smaller pieces, and DeFi Saver automates repay on Aave. Soft Landing is an ownable isolated market where each step is a small, fixed sale with a plain warning before it, plus a meter that shows how far the next step is. Research verdict: low novelty; the warning loop and the ownable market are the value.
Unlocked when your app is paid in full
No borrower should lose a big slice of what they own in one block while they sleep.
The meter One number on the home screen: how far the price can fall before the next small step, in percent and dollars.
The warning A message before every step with the price it fires at and two buttons: top up or repay. Nothing else attached.
The landing report After a rough week: how many steps fired, what they cost, and what a single cliff liquidation would have cost instead.
Unlocked when your app is paid in full
Cost per use: unlocked when your app is paid in full.
The landing report is the hook: borrowers share how much a rough week cost them in small steps against what one cliff liquidation would have cost. Lending and DAO treasury communities pass the meter around after every crash.
Unlocked when your app is paid in full
Unlocked when your app is paid in full
Costs and tools are estimates at the time of writing. General information only, not legal or financial advice.
Nine routes from one vessel. Tap a port to open its chart.
Everyone who has borrowed against crypto has a liquidation story, and most of them happened at night in one block. Owning Soft Landing means you run a lending market where that story changes: loans unwind in small steps, a warning arrives before each one, and borrowers can stop it with one tap. You set the collateral, the step size and the warning lead, and you earn from plans and a share of interest. Start with one community that got hurt in the last crash.
You start with one isolated market, one collateral and a conservative loan to value, with audited parts and a size cap. The Rules screen is a short form. Grow the cap only as the market proves itself, and keep it small until it has.
It can. A gap faster than keepers can act hits the backstop liquidation, and the app says so before anyone borrows. Your job is honest wording, realistic spacing and a modest max loan to value, not a promise that liquidation cannot happen.
Curve's design works but is hard to read for a normal borrower. Your edge is the warning before each step, a meter anyone understands and a market run for a community you know. Lead with that, and credit Curve openly.
It depends where you live and who you serve. Many owners run it for a known group, take local advice before marketing widely and never promise returns to lenders. The app avoids words like guaranteed or liquidation free on purpose.
Monthly Cushion and Treasury plans plus a reserve share of borrow interest from every market you run.
Illustrative stages, not a forecast. Results depend on you and the market; nothing here is guaranteed.
LIVE DEMOLock content behind a fraction-of-a-cent USDC payment, on your own Arc contract. Deploy it, become the onchain creator.
 LIVE DEMO
Take pay-what-you-want USDC tips on Base, with a live supporters feed read straight from chain. No Circle account, no backend.
 LIVE DEMO
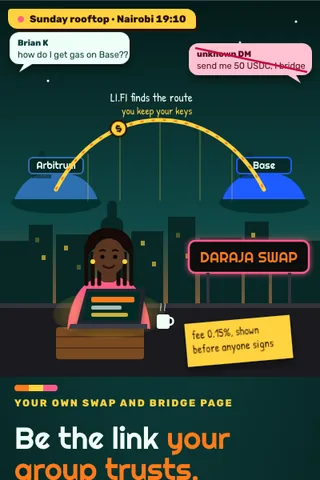
Your own swap/bridge front-end. Integrator fee optional and disclosed.
 LIVE DEMO
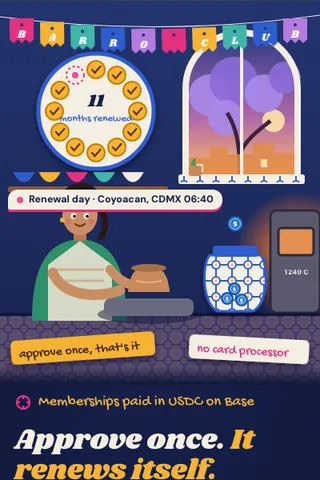
Recurring USDC on Base. Members approve once, it renews itself. No card processor, no contract.
 LIVE DEMO
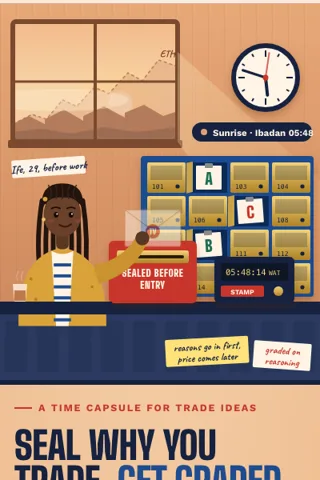
Write why you entered a trade, seal it with the timestamp, and get graded on reasoning, not luck.
 LIVE DEMO
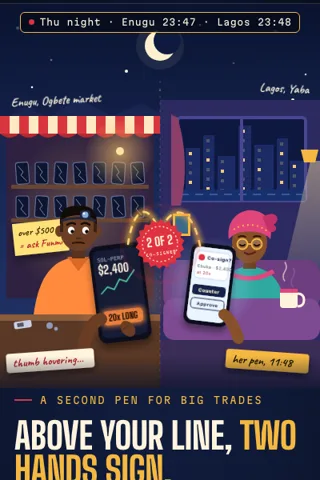
Let a trusted mentor co sign your risky trades above a size you choose.
 LIVE DEMO
Your perp bot follows your rules, and every rule you kept becomes a public, provable track record.
 LIVE DEMO
A tilt brake that delays your trades after losses until you answer one honest question.